

Money BetterThisWorld: 15 Smart Strategies for Purposeful Wealth in 2026
Ever finished the month wondering where your pay went? You’re not alone. Millions of people feel that way. Money BetterThisWorld offers a fresh way out. It treats money as a tool for a good life. It isn’t a scoreboard.
This guide shares 15 smart strategies for purposeful wealth. You’ll learn personal finance strategies, money management tips, and wealth building strategies in plain words. A 30-day plan at the end helps you start today. Amounts use your local currency. Rules of thumb vary by country.
What Is Money BetterThisWorld?
Think of money as a bus. It should take you somewhere that matters. Money BetterThisWorld asks you to pick the destination first. Then you choose how to pay for the trip. This is the heart of purpose-driven financial decisions.
The idea is simple. Earn with care. Save with a goal. Invest with patience. Spend in line with your values. Then use some of your wealth creation to lift others too. That’s the full loop.
The Meaning of Money BetterThisWorld
The Money BetterThisWorld meaning is easy to state. Use money on purpose, and let it support your goals, your people, and your world. Net worth matters. Yet the question “What is my money for?” matters more. It builds financial awareness and responsibility from day one.
Key Principles of Purposeful Wealth
Purposeful wealth rests on five ideas: awareness, financial responsibility, clear planning, long-term wealth growth, and positive impact. Each one feeds the next. Track what you earn. Own your choices. Plan with goals. Grow with time. Then give back where you can. This is how to build purposeful wealth step by step.
Purposeful Wealth vs. Financial Independence
Financial independence means your money covers your living costs without a job. Purposeful wealth is wider. It asks if your money matches your values, even while you work. You can pursue both. Many people reach independence faster because purpose keeps them steady.
| Idea | Main Question | Main Goal |
| Financial independence | Can I stop working? | Freedom from paid work |
| Purposeful wealth | Does my money fit my life? | Meaning, security, impact |
Why Money BetterThisWorld Matters in 2026
Living costs keep rising in many places. Jobs shift fast. Prices swing. In this climate, personal financial planning in 2026 is a survival skill. Guesswork no longer works.
A clear purpose gives you calm. You say no to junk spending more easily. You say yes to what counts. That builds financial resilience when surprises hit.
The Shift From Wealth Accumulation to Financial Well-Being
Old advice said, “Earn more, buy more.” Many people ended up tired and in debt. Today the focus has moved to financial well-being. Can you sleep well? Can you handle a surprise bill? That’s sustainable wealth accumulation. It beats chasing a big number with no plan.
How Financial Decisions Affect Quality of Life
Every choice shapes your days. A smart habit buys you time and peace. A sloppy one buys you stress. Money worries hurt sleep, health, and even relationships. Good financial planning lowers that load. This link between financial wellness and life satisfaction is real and strong.
Understanding Your Current Financial Position
You can’t plan a trip without knowing where you stand. Start with a clear snapshot of your money. Look at what comes in, what goes out, and what you owe.
Don’t judge yourself. Just look. Numbers are only facts. Facts give you power to change things.
How to Conduct a Personal Financial Audit
Strategy 1: Audit your finances. List your income, fixed bills, flexible spending, debts, savings, and investments. Use your last three months of statements. This shows how to track monthly expenses without guessing. Most people find a few surprises. A forgotten subscription is a classic one.
Key Financial Metrics Everyone Should Track
Strategy 2: Track the numbers that matter. A few numbers tell your story. Check them monthly. These are common starting points, so adjust them for your country and life.
| Metric | Common Target |
| Savings rate | About 20% of income |
| Emergency fund | 3 to 6 months of expenses |
| Debt payments vs. income | Under about 36% |
| Net worth | Rising each year |
How Income and Living Costs Affect Your Budget
Your budget is a tug of war. Income pulls one way. Rent, food, and transport pull the other. If you live in a costly city, the usual rules may need a tweak. Good income and expense tracking shows where the gap is. Then you can raise income or trim costs.
The Psychology of Money and Financial Habits
Money isn’t only math. Feelings drive many choices. Behavioral finance psychology shows that stress, pride, and habit often beat logic.
The good news? Habits can change. Small shifts add up. These financial habits for long-term success are learned, not born.
Emotional Spending and Impulse Purchases
Strategy 3: Master your money mindset. Bored? Sad? Happy? Many of us shop to feel better. Try a 48-hour wait rule for any non-essential buy. Often the urge fades. That’s emotional spending control in action, and it protects your smart spending habits.
Lifestyle Inflation and Social Comparison
Raises tempt us to upgrade everything. A bigger car. A fancier flat. That’s lifestyle creep. Here’s how to avoid lifestyle inflation: save at least half of every raise. Also, remember that social media shows highlights, not debts. Practice mindful spending habits and compare only with your past self.
Common Habits That Cause Budgets to Fail
Budgets fail for simple reasons. They’re too strict. They ignore irregular costs like car repairs. Or they’re never reviewed. Build in a small fun fund and a buffer for surprises. A budget you can live with beats a perfect one you quit.
See Also : Mastering Your Health: A Simple Guide to Smarter Daily Habits in 2026
How to Build a Purposeful Financial Plan
A plan turns wishes into steps. It’s your map. Financial planning for beginners can be simple. Pick goals, set dates, and choose actions.
Keep the plan short enough to remember. Review it every few months. Life changes, and your plan should too.
Setting SMART Financial Goals
Strategy 4: Set SMART goals. SMART means specific, measurable, achievable, relevant, and time-bound. “Save more” is vague. “Save 3,000 in 12 months” is clear. These financial goal-setting strategies keep you moving. They also set your financial goals in order of importance.
Short-Term Financial Goals
Short-term goals take under a year. Think starter savings, a first budget, or clearing a small card balance. These quick wins build trust in yourself.
Medium-Term Financial Goals
Medium-term goals take one to five years. Examples include a home deposit, a course, or a small business. They need steady monthly saving.
Long-Term Financial Goals
Long-term goals take five years or more. Retirement and financial freedom planning live here. Start early. Time does much of the heavy lifting.
Aligning Your Spending With Personal Values
Strategy 5: Align spending with values. List your top three values. Maybe family, health, and learning. Then check your last month of spending. Does the money match? This is how to align spending with personal values. It brings financial goal alignment and less regret.
Creating a Realistic Financial Roadmap
A roadmap links today to your big goals. Break each goal into yearly, monthly, and weekly steps. Add a review date every quarter. Be kind to yourself when life interrupts. A realistic path beats a rushed one. It’s the base of sustainable personal wealth growth.
Budgeting Strategies That Work in 2026
Strategy 6: Choose the right budgeting method. No single plan fits all. Smart budgeting methods differ in style, effort, and flexibility. Pick one that matches your habits.
Try it for three months. Then adjust. Learning how to manage personal finances is a skill. Skills improve with practice.
The 50/30/20 Budgeting Rule Explained
The 50/30/20 budgeting rule splits after-tax income three ways. Half goes to needs. Thirty percent goes to wants. Twenty percent goes to savings and debt payoff. With an income of 2,000 a month, that means 1,000, 600, and 400. It’s a friendly start for beginners.
Zero-Based Budgeting
The zero-based budgeting method gives every unit of money a job. Income minus planned spending equals zero. Savings count as spending here. It’s great if you want tight control or have debts to clear.
Pay-Yourself-First Budgeting
The pay yourself first strategy moves savings out the moment you’re paid. You spend what’s left. It’s often credited to Warren Buffett’s advice to save first and spend the rest. Automation makes it painless.
Values-Based Budgeting
Values-based budgeting puts more money into what you love and cuts what you don’t. Spend freely on your top priorities. Trim the rest without guilt. It fits Money BetterThisWorld perfectly.
Choosing the Best Budgeting Method for Your Income
Low income? Zero-based budgeting gives control. Steady income and busy life? Try pay yourself first. Want simplicity? Use 50/30/20. Mix methods if needed.
| Method | Best For | Main Drawback |
| 50/30/20 | Beginners | Too loose for high-cost cities |
| Zero-based | Tight budgets, debt | Takes more time |
| Pay yourself first | Busy people | Needs a stable income |
| Values-based | Purpose seekers | Needs honest self-review |
How Much Money Should You Save Each Month?
This is the top question beginners ask. The honest answer is: it depends. Your goals, costs, and income all matter. Still, a good rule gives you a start.
Think in percentages, not fixed amounts. Percentages grow as you earn more. They also work in any currency.
Understanding the 20% Savings Rule
Many experts suggest saving about 20% of income. That’s a common answer to how much money to save each month. It’s a guide, not a law. Some people can only manage 5% for now. That’s fine. Begin there and climb.
How to Calculate Your Monthly Savings Target
Strategy 7: Set a monthly savings target. Take your take-home pay. Multiply by your chosen rate. Earn 1,500 and want 15%? That’s 225. Set monthly savings targets and automate them. These saving money tips work because you never see the money.
See Also : Newstown CraigScott Capital (2026): The Ultimate Investor Guide to Verified Facts and Risks
Adjusting Savings Goals for Income and Living Costs
Life isn’t equal for everyone. High rent can squeeze your rate. A big raise can lift it. Adjust each year. If you can’t hit 20%, add 1% every few months. Slow and steady still wins.
Building an Emergency Fund Without Sacrificing Quality of Life
Strategy 8: Build an emergency fund. Here’s how to create an emergency fund without pain. Start with one small month of basics. Then grow toward three to six months. Park it in a safe, easy-access account. Good emergency fund planning keeps you from using credit when trouble strikes.
Smart Debt Management Strategies for Financial Stability
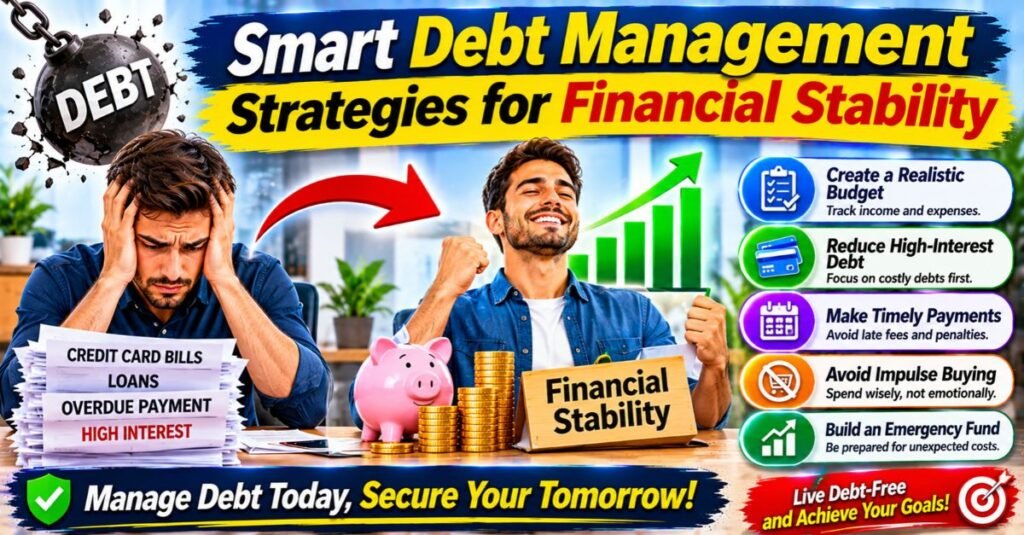
Strategy 9: Manage debt with a clear plan. Debt isn’t always bad. But unmanaged debt drains financial security. A written plan turns worry into action.
Start by listing every debt. Note the balance, rate, and minimum payment. Strong debt management strategies begin with facts. Then you pick a method.
Understanding Good Debt and Bad Debt
The good debt vs bad debt idea is simple. Good debt may build future value. Think a fair-rate home loan or study loan with real job prospects. Bad debt funds things that lose value, often at high rates. Credit cards and payday loans are common examples.
Debt Snowball vs. Debt Avalanche Methods
In debt snowball vs debt avalanche, snowball pays the smallest balance first. It gives quick wins. Avalanche pays the highest rate first. It saves more interest. Either works if you stick with it. Good debt repayment planning is about consistency.
| Method | How It Works | Best For |
| Snowball | Smallest balance first | Motivation |
| Avalanche | Highest rate first | Saving interest |
| Hybrid | Mix of both | Balance |
Should You Pay Off Debt Before Saving Money?
Do both, in order. First, save a small starter emergency fund. Then attack high-rate debt hard. Low-rate debt can wait while you save and invest. Paying off a 20% card is like earning a safe 20%. Few investments can promise that.
How to Avoid Common Debt Management Mistakes
Common errors include paying only the minimum, taking new debt while repaying old debt, and ignoring fees. Another is skipping the emergency fund, which leads to fresh borrowing. Call your lender early if you struggle. Many offer help.
Investing Strategies for Long-Term Wealth Growth
Saving protects you. Investing grows you. Inflation slowly shrinks idle cash. So smart investment planning matters for how to build long-term wealth.
Start simple. Learn the basics. Never invest money you’ll need within a few years. Risk and reward travel together.
See Also : Hosted Event PBLGamevent 2026: The Ultimate Guide to Successful Gaming Events
Major Investment Options for Beginners
Beginners usually meet four main choices: stocks, funds, bonds, and property. Each has a different job. Understanding them helps you mix them wisely. Choices and tax rules differ across countries, so check local rules.
Stocks and Exchange-Traded Funds (ETFs)
Stocks give you a small share of a company. Exchange-traded funds hold many stocks or bonds in one package. For most beginners, broad, low-cost ETFs are easier than picking single stocks.
Bonds and Fixed-Income Investments
Bonds are loans to governments or companies. They pay interest and usually swing less than stocks. They help with wealth preservation strategies and calmer portfolios.
Real Estate Investments
Property can pay rent and rise in value. It also brings costs, repairs, and less flexibility. If buying feels too big, some countries offer property funds with smaller entry amounts.
How to Start Investing With Small Amounts
Strategy 10: Start investing early, even small. Investing for beginners with little money is possible today. Many platforms accept tiny deposits. Time beats size because of compound growth. The table assumes an 8% yearly return, which isn’t guaranteed.
| Starting Amount | Value After 20 Years at 8% |
| 1,000 | About 4,661 |
| 2,500 | About 11,652 |
| 5,000 | About 23,305 |
Risk Management and Portfolio Diversification
Strategy 11: Diversify and manage risk. Don’t put all your eggs in one basket. Risk management and portfolio diversification spread your money across assets, sectors, and regions. That’s investment portfolio diversification at work. Past returns don’t promise future results. Think about risk-adjusted investment returns, not just the highest gain.
Common Investing Mistakes to Avoid
Watch for panic selling, trying to time the market, chasing hot trends, and ignoring fees. Another trap is putting everything into one idea. Boring habits often win. Regular deposits, low costs, and patience beat clever tricks.
Modern Income Strategies for Building Wealth in 2026
Saving only goes so far. Earning more gives you more room to move. Today, tools and platforms open many doors. This is smart income diversification.
Start with your main job. Then explore side options. Be careful with promises of fast money. Real income takes real effort.
Increasing Your Primary Income
Strategy 12: Grow your main income. Here are proven ways to increase personal income. Learn in-demand skills. Earn certifications. Ask for more responsibility. Practice negotiation and prepare facts before you ask for a raise. Small skill gains can lead to big pay jumps over time.
Developing Additional Income Streams
Strategy 13: Build extra income streams. Freelancing, consulting, tutoring, digital products, and content creation are popular. These multiple income streams soften shocks if one source dries up. Start small. Pick something that fits your skills and free hours.
Passive Income: Benefits, Risks, and Realistic Expectations
The passive income benefits and risks both deserve a look. Benefits include flexibility and extra security. Risks include slow starts and uncertain returns. Many passive income ideas need months of work first. Think of it as a garden. You plant, water, and wait.
Technology and Digital Tools for Better Money Management
Apps now do tasks that once took hours. They track spending, send reminders, and flag trends. Good digital financial management saves time and reduces errors.
Still, tools don’t replace judgment. Use them as helpers. Keep your goals in charge.
AI-Powered Personal Finance Tools
Strategy 14: Use smart tools and stay safe. AI-powered financial tools can sort expenses, spot waste, and suggest savings. Treat their advice as ideas, not orders. Check the facts before acting. Don’t share sensitive details you don’t have to.
Digital Banking and Budgeting Apps
Digital banks often have lower fees and faster transfers. Budgeting apps link accounts and show spending in one place. Pick tools with strong reviews and clear privacy rules. These help with personal wealth management and financial literacy alike.
Protecting Your Money From Online Scams and Fraud
Scams are getting smarter. Use strong passwords and multi-factor sign-in. Never click unknown links. Banks won’t ask for your PIN by message. Good cybersecurity and financial fraud prevention habits protect your savings. Check accounts weekly.
See Also : Voomixi com Review 2026: Is It Legit, Safe, or a Scam?
How Purposeful Wealth Improves Life Satisfaction
Research suggests money lifts happiness most when it removes stress and opens choices. After basic needs are met, the boost often gets smaller. Experiences, health, and relationships matter more.
Purposeful wealth aims at these things. It builds economic well-being without chasing endless stuff. That’s a calmer, kinder kind of success.
Balancing Financial Security With Personal Happiness
Saving for tomorrow matters. Enjoying today matters too. Set aside a small fun budget, guilt-free. Balance protects you from burnout. It keeps you on the plan for years. That’s how financial security and stability and joy can coexist.
Using Money to Support Your Values and Priorities
If family matters, fund time together. If learning matters, fund courses. Let your top values guide big purchases. Ask, “Will this still matter next year?” That one question sharpens financial decision-making skills fast.
Creating Positive Social and Community Impact
Strategy 15: Use your wealth to make an impact. Give, mentor, or support local businesses. Consider ethical investing and socially responsible wealth creation. Even small gifts add up. This community-focused financial impact is the final piece of Money BetterThisWorld.
Common Money BetterThisWorld Myths and Financial Mistakes
Myths cost people real money. Some sound wise but lead you astray. Clearing them up saves years of frustration.
Here are the big ones. Look for what fits your own life. No rule is perfect for everyone.
Does Building Wealth Require a High Income?
No. Habits matter more than pay. A person earning less but saving steadily can beat a big earner who overspends. Consider two people with the same salary. One invests each raise. The other upgrades every year. Ten years on, the first is far ahead.
Why Following Every Budgeting Rule Does Not Work
Rules are tools, not laws. A rule built for one country may not fit yours. If 50/30/20 breaks your budget, change the split. Keep what works. Drop what doesn’t. A flexible plan survives real life.
Financial Mistakes That Slow Down Long-Term Growth
The usual suspects slow people down: no goals, high-interest debt, no emergency fund, and ignoring investing. Emotional choices also hurt. Fix one at a time. Small repairs build sustainable wealth building over the years.
When Traditional Financial Rules May Not Apply
Some situations need special care. Irregular income, supporting extended family, or living where banking is limited can change the rules. Build bigger buffers if income swings. Adapt the advice. Seek a local, licensed adviser for big decisions.
Your 30-Day Money BetterThisWorld Action Plan
Knowledge needs action. This plan turns the ideas into four easy weeks. Each week has one clear focus.
Don’t aim for perfection. Aim for it. Even partial progress changes your path.
Days 1–7: Review Your Finances and Spending Habits
Track every expense for seven days. Calculate your net worth. Review subscriptions and cancel the ones you don’t use. By the end of the week, you’ll know where your money goes.
Days 8–14: Create a Budget and Savings Plan
Choose a budgeting method. Set a savings target. Automate a transfer on payday. Start your emergency fund, even with a tiny amount. These are the building blocks of saving money tips that last.
Days 15–21: Reduce Debt and Explore Growth Opportunities
List your debts and pick a snowball or avalanche. Make one extra payment. Then research low-cost investing options and one way to boost income. Learning counts as progress.
Days 22–30: Review Progress and Improve Your Financial Strategy
Compare your numbers to week one. Celebrate your wins. Adjust goals that felt too hard or too easy. Finish by writing a 12-month roadmap. Revisit it every quarter.
The Future of Money BetterThisWorld and Personal Finance
Personal finance is becoming more personal. Tools learn your habits. Advice gets tailored. People also want their money to reflect their beliefs.
Those who combine smart tools with clear purpose should do well. Stay curious. Keep learning. Build future financial preparedness now.
Emerging Trends in Financial Planning
Expect more personalized plans, automated saving, and rising interest in ethical funds. Financial education is spreading too. Newer products may bring both benefits and risks, so test small and learn first.
The Growing Role of Technology in Wealth Management
Robo-advisers, instant payments, and AI helpers are changing how people manage money. They lower costs and widen access. Yet security and good judgment stay vital. Technology works best as a partner to your plan.
Frequently Asked Questions
What Does Money BetterThisWorld Mean?
It’s a philosophy of using money with intention. You align choices with your goals and values. You also consider the wider impact of your wealth on others.
How Much Should a Beginner Save Each Month?
Many experts suggest 20% of income. If that’s too much right now, start with 5% to 10%. Raise it a little every few months until you reach your target.
Is the 50/30/20 Budgeting Rule Realistic in 2026?
It can be, but not for everyone. In high-cost areas, needs may exceed 50%. Treat it as a starting framework. Change the percentages until the plan fits your life.
Why Do Most Personal Budgets Fail?
Most budgets fail because they’re too strict, too complex, or never reviewed. Add a fun fund. Keep it simple. Review monthly. A flexible budget lasts longer than a rigid one.
Should I Save Money or Pay Off Debt First?
Build a small emergency fund first. Then pay off high-interest debt quickly. After that, balance saving and investing. Low-rate debt can wait while you build wealth.
Can Beginners Build Wealth With a Small Income?
Yes. Consistency beats size. Save a steady slice, avoid costly debt, and invest regularly. Grow your skills to lift income over time. Small steps compound.
How Can I Start Investing With Little Money?
Pick a low-cost, diversified fund or ETF on a trusted platform. Start with a small, regular deposit. Learn as you go. Only invest money you won’t need soon.
Conclusion
Money BetterThisWorld is about more than a bigger balance. It’s about a life where your money supports what you value. Awareness, financial responsibility, smart planning, and patience form the base. Purpose ties it together.
You don’t need to do everything at once. Pick one strategy today. Maybe track your spending or set up an automatic transfer. Small, steady steps lead to lasting financial well-being. Start now, and let each choice move you toward the life you want.




One Comment